RALEIGH, N.C. (AP) — Carolina Hurricanes winger Seth Jarvis shed his yellow no-contact jersey Thursday as he continues his recovery from offseason shoulder surgery.
The top-line forward for the reigning Stanley Cup champions had surgery on his right shoulder June 24. The surgery was to correct tears in his labrum and rotator cuff, and he was estimated to be out about 4-6 months in his recovery.
Jarvis had been skating with the team in the yellow jersey since the start of preseason camp.
“It's probably the biggest step I've had so far, getting out of that, being able to take contact now,” Jarvis told reporters after the team's skate before hosting Vancouver on Thursday night. “Now it's just a matter of getting comfortable, making sure it's ready to go.”
Jarvis told The Associated Press in late September he wanted to be back for a trip to Finland for Carolina's two-game set against Seattle on Nov. 12 and 14, though he raised the possibility of returning by the end of October.
Jarvis was originally hurt in a November 2023 game and had spent years managing the injury, from wearing a protective harness to changing his positioning when he slept through the night.
See AP’s full NHL coverage here
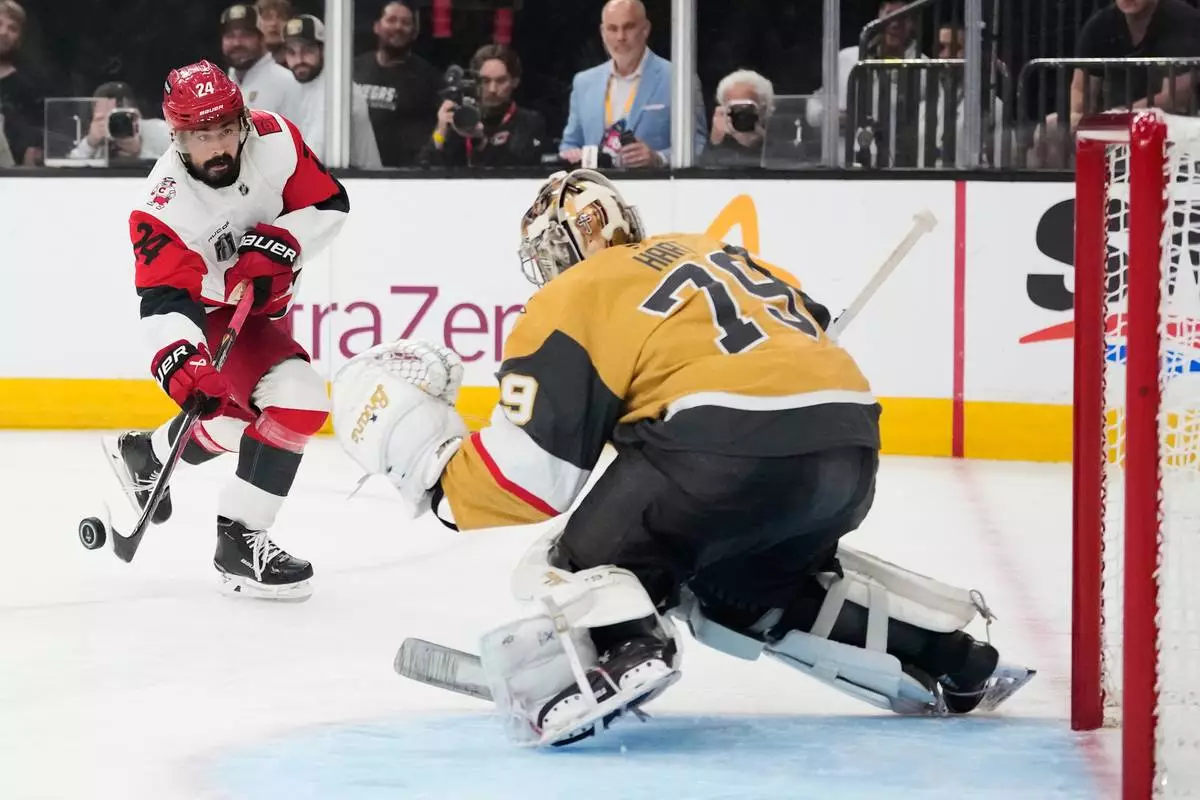
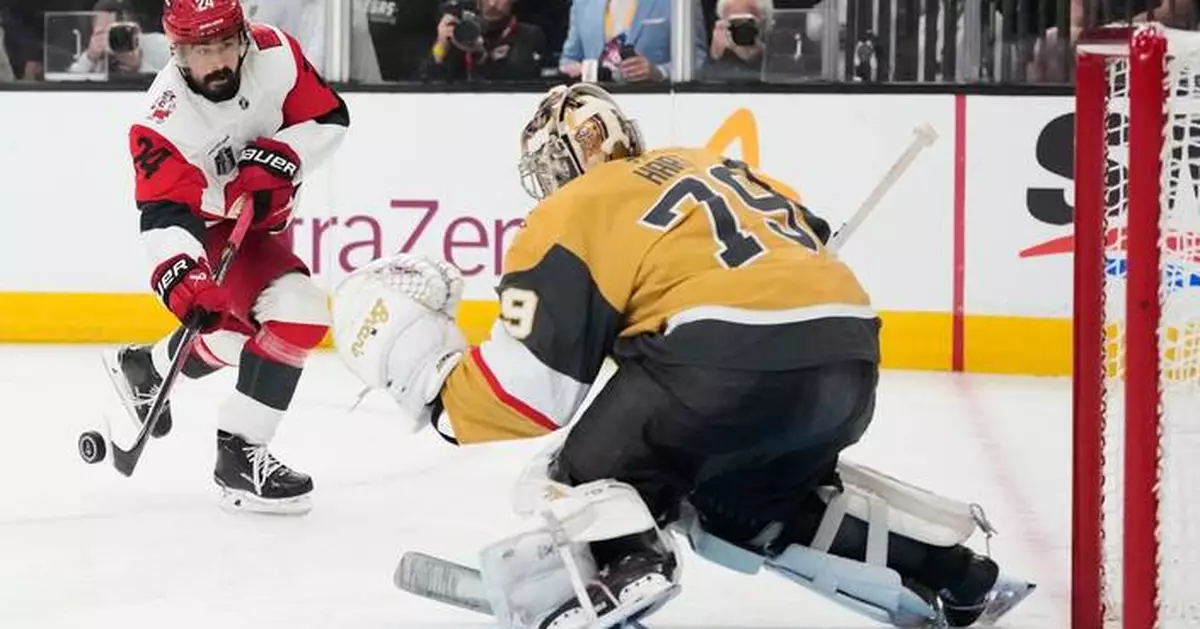
FILE - Carolina Hurricanes right wing Seth Jarvis (24) shoots in front of Vegas Golden Knights goaltender Carter Hart (79) during the third period in Game 6 of the NHL hockey Stanley Cup Final series, Sunday, June 14, 2026, in Las Vegas. (AP Photo/John Locher, File)
NEW YORK (AP) — Whether you realize it or not, your child may be enrolled in a “Trump Account.”
Rolled out earlier this year, the Trump Accounts program allows parents to claim special investment accounts for children who are 18 years old or younger. And some babies are eligible to receive a one-time $1,000 contribution from the government.
Now, because of automatic enrollment highlighted Wednesday by President Donald Trump, the Treasury Department says every eligible child with a valid Social Security number has a Trump Account. But parents and legal guardians would still need to formally activate the accounts if they haven't already.
Here’s what we know.
The accounts are a savings tool that invests money in the stock market on a child’s behalf. The child can’t access the money until they turn 18 and can use it only for specific purposes, such as paying tuition, starting a business or making a down payment on a home. Families can activate an account through the program’s trumpaccounts.gov website or its mobile phone app.
The government will make a $1,000 contribution for some babies after the account is claimed. To qualify for the $1,000 seed money, a baby must be a U.S. citizen, have a Social Security number and be born between Jan. 1, 2025, and Dec. 31, 2028 — covering Trump's current term.
Any parent — regardless of their immigration status — can open an account for a qualifying child. Parents of older children also are encouraged to open accounts. Even though they aren't eligible for the government's $1,000 contribution, some older children are eligible for seed money of $250 drawn from separate investments from wealthy donors.
Otherwise, family contributions will need to come out of pocket. Parents can contribute up to $2,500 annually in pretax income, much like retirement accounts. Employers, relatives, friends, local governments and philanthropic groups can also pitch in. Yearly contributions are capped at $5,000, although contributions from governments and charities don’t count toward that total.
Private banks and brokerages will manage the money. When the accounts were originally conceived, investments were restricted to broader index funds. But with updated rules from the Treasury Department late last month, eligible wealthy investors can now also donate stock from individual companies.
With automatic enrollment, Trump said 70 million children will now have the accounts, up from 8 million created since their launch in July.
Researchers from the Brown School's Center for Social Development at Washington University in St. Louis advocated for the automatic enrollment. And Jin Huang, co-director of the center, called the administration's move “a big step."
“Automatic enrollment is the most important policy design feature for early wealth building programs, in order to ensure full inclusion of all eligible children," said Huang, citing research from his team.
Still, he says, more work needs to be done. Parents and legal guardians need to formally claim the accounts to activate them — as well as elect the $1,000 seed money if they're eligible — and Huang says “each of these steps will lower the participation,” with particular barriers facing low-income families who may not already have access to similar investments.
When Trump Accounts were first rolled out, investments were initially restricted to broad index funds — in theory to decrease risk while still yielding incremental growth. But among additional updates to the program, eligible wealthy investors can now also donate stock from individual companies.
“It’s a way to encourage participation in the program,” explained Nathan C. Goldman, a professor of accounting at North Carolina State University. He said many of the world’s wealthiest people don’t have “a whole lot of liquid cash sitting around” and might instead turn to shares.
Still, he notes, individual stocks are more volatile than indexes. And families wouldn’t get a say about which companies might donate to their children’s portfolios.
It’s important to note that the child won’t be able to access the money until they turn 18, except in rare circumstances. So the money can’t help with immediate expenses.
But once a beneficiary of a Trump Account turns 18, they can choose to use the money from it however they want. Trump account beneficiaries can also choose to roll the investment over to a Roth IRA account.
“You’re extending the life of this thing beyond the 18 years; you’re going all the way out into the child’s potential retirement,” said Myranda Fabian, a certified financial planner with Plante Moran Financial Advisors.
Moving the earnings from a Trump Account to a Roth IRA will be subject to taxation. Roth IRA accounts allow earnings to grow and to be withdrawn free of taxation when an adult reaches retirement age.
The 529 accounts are meant to invest for qualified educational expenses, such as college tuition, trade school and student loans, among other expenses. They grow tax-free, while investment earnings from Trump accounts will be taxed when withdrawn, and 529 account funds can be transferred to eligible family members.
Still, they're specifically limited to spending on education. In contrast, there are more options to park money from Trump Accounts after a child turns 18.
Custodial brokerage accounts, on the other hand, are taxable investments with no contribution or withdrawal limits, unlike Trump Accounts. But similar to Trump Accounts, beneficiaries of custodial brokerage accounts have full control of the account once the child turns 18, and there are no rules on how they can spend the money.
Choosing an investment account that is better suited for a child’s future depends on each parent’s goals, said Kate Ashford, lead wealth writer at NerdWallet.
“The account that you’re using for savings is really going to depend on why you’re saving money,” Ashford said.
If parents are looking to focus on funding the education of their children, she added, 529 accounts continue to be the most beneficial.
Backers of Trump Accounts say they want to introduce more people to the stock market and give even children born into poverty a chance to benefit from it.
But critics say the accounts also fail to offset the cuts the Trump administration and congressional Republicans have made to other programs that benefit young people and the adults in their lives, including food assistance and Medicaid. And even with government contributions, some warn that the Trump Accounts could widen the wealth gap.
Goldman sees Trump Accounts as a tool to diversify — and notes that at the end of the day, they're another option families can consider when making investments for their children, with solid tax advantages.
Still, affluent families will be more likely to afford the full scope of additional, out-of-pocket investments, Goldman said. A total contribution of $5,000 each year, for instance, would add up to $90,000 for one child over 18 years — and even with starting seed money for some children, or options to make smaller investments, inequities remain.
“It’s designed — especially with this $1,000 seed money — to be ‘an account for everybody,’" Goldman said. “But only some people are gonna be able to take advantage of this. Only some people are going to have that ability to do that."
AP Writer Moriah Balingit contributed. Grantham-Philips reported from Chicago.
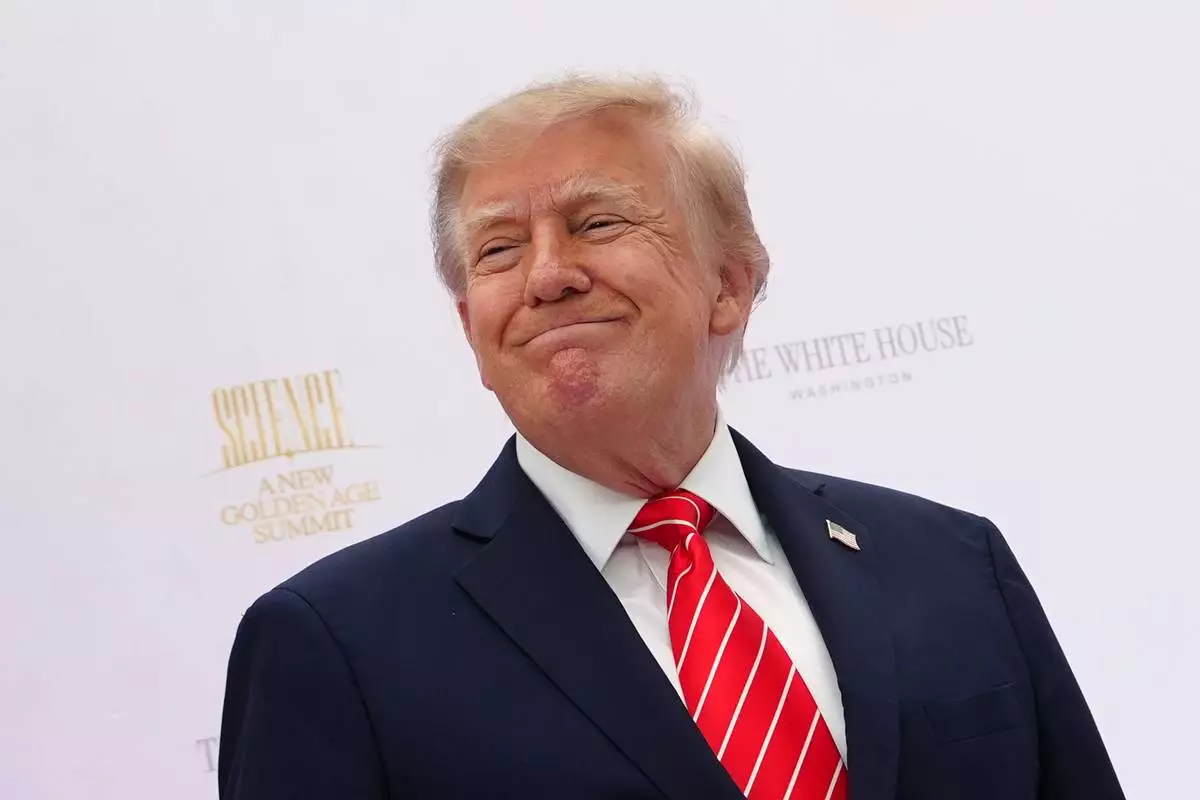
President Donald Trump arrives to speak during an event at the U.S. Institute of Peace, Thursday, Oct. 8, 2026, in Washington. (AP Photo/Julia Demaree Nikhinson)