Thanksgiving isn't for a few weeks, but there's already a feast of good matchups in women's basketball and the season is barely a week old.
No. 1 South Carolina will face third-ranked USC on Sunday for the third time in the past 12 months. The Gamecocks won the first two meetings, including an NCAA Tournament second-round victory last season. The Trojans will have JuJu Watkins back in the lineup this time as the sensational junior missed both of last season's game while she was still rehabbing an ACL injury she suffered 20 months ago.
The Gamecocks have looked dominant so far in their first two games, beating ranked opponents Maryland and North Carolina. The victory over the Tar Heels was by 45 points — the team's largest over a Top 25 team, according to ESPN.
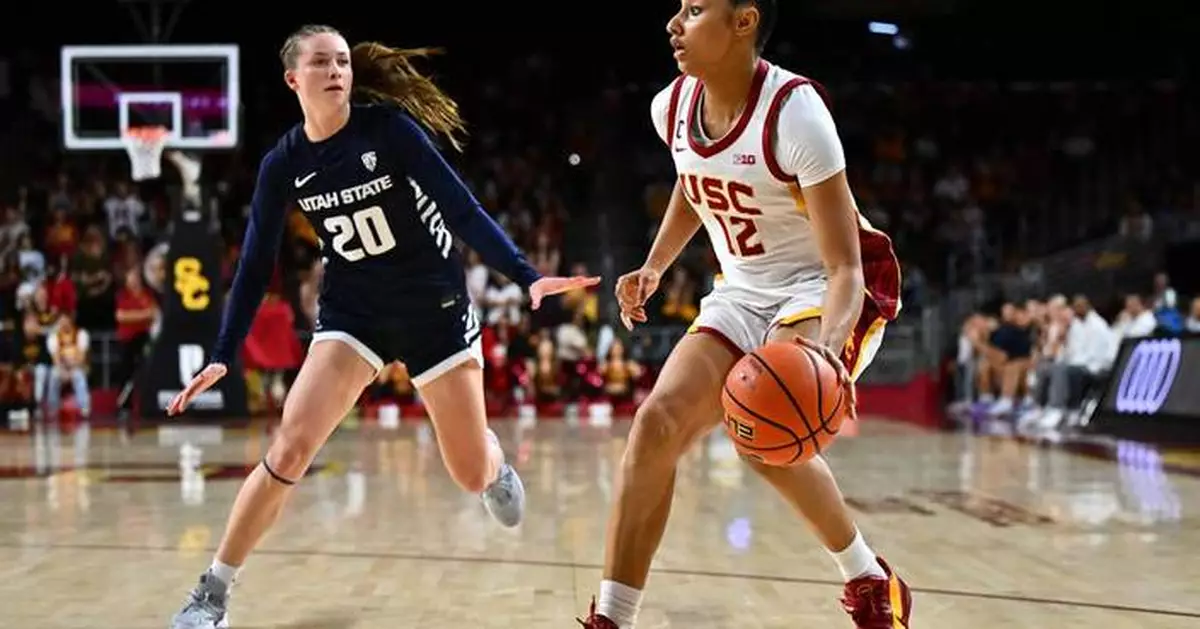
Watkins has looked strong in her return. She averaged 26.5 points, 10.5 rebounds, 4.0 assists and 3.5 steals in easy wins over UNLV and Utah State.
South Carolina had its own return with Chloe Kitts, who missed last season with an ACL injury also. She had 17 points and 10 rebounds in the victory over the Tar Heels. It was Kitts' first double-double since she had 15 points and 11 rebounds against Maryland in the 2025 NCAA Tournament.
Both the Gamecocks and Trojans play before Sunday's showdown.
That same day No. 8 Vanderbilt and Mikayla Blakes will visit 10th-ranked Iowa. The Hawkeyes are coming off a loss at UConn. Sunday's game will be an opportunity for Vanderbilt to go on the road and play in a loud road environment before the tough SEC schedule that awaits them in the new year.
The Commodores are 3-0 and have scored more than 100 points in each of their first three contests, albeit this will be a giant step up in competition.
It's a busy week for some of the top teams in the Ivy League as Columbia, Princeton and Penn all play ranked teams. The Lions will host No. 2 Michigan on Thursday night — the highest ranked opponent ever to visit Columbia before visiting No. 19 Maryland on Sunday. Princeton has a busy week with a home game against Villanova on Tuesday before a west coast trip to face Pepperdine and No. 10 UCLA. Penn will host No. 23 North Carolina on Saturday.
The U.S. Postal Service announced Monday that former Tennessee coach Pat Summitt will be honored with a stamp in 2027 along with baseball great Willie Mays.
Summitt's stamp features a portrait of the Hall of Fame coach, who died at age 64 in 2016. She led the Lady Vols to eight NCAA championships and 1,098 victories in her career, which was cut short after she was diagnosed with early onset dementia, Alzheimer’s type before the 2011-12 season. She retired after that season at age 59 and started the Pat Summitt Foundation.
Sign up for Top 25 poll alerts here, visit the Top 25 here and see AP’s full college basketball coverage here
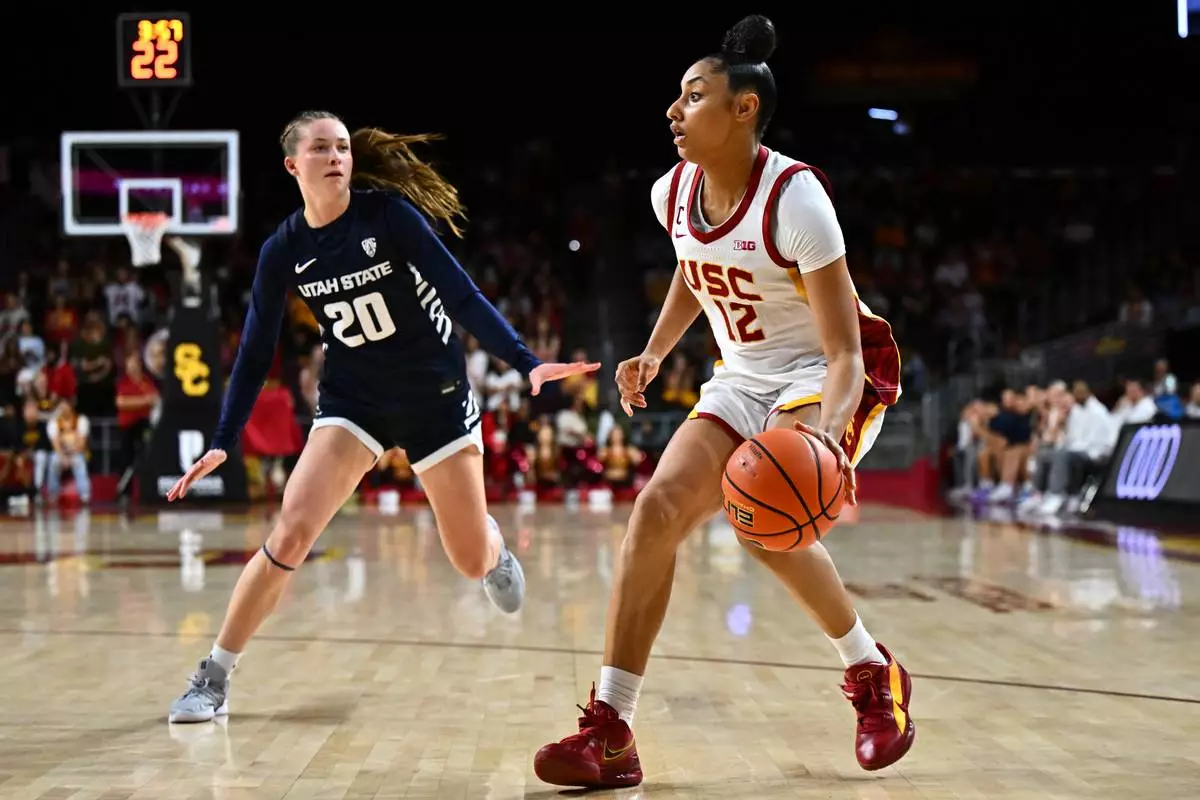
Southern California guard JuJu Watkins (12) drives the ball past Utah State guard Kylani Rookstool (20) during the second half of an NCAA college basketball game Sunday, Nov. 8, 2026, in Los Angeles. (AP Photo/William Liang)
With cash and bond yields at their highest levels in over 15 years, many investors wonder if they should favor these higher-yielding options over stocks.
Here are answers to some questions investors might have about how to approach asset allocation in an era of 5% CD yields.
The yields on cash products are compelling today, and cash investors do not have the potential for principal volatility. That’s particularly appealing because we’ve seen losses for some bond investors over the past few years and so far in 2026. Additionally, our annual diversification research has shown that cash is a solid diversifier for equities, on par with bonds.
But cash yields are fleeting: Cash investments are short-term loans to various entities. If interest rates drift down, the high yields may disappear as higher interest rate loans are retired. If you lock in a longer-term CD, you can benefit from that high yield longer. But if you’re in a money market mutual fund or high-yield savings account, your yield will fluctuate based on the prevailing interest rate environment.
Another consideration is inflation risk. Over very long periods, cash yields sometimes beat inflation, but not always. That risk is top of mind for investors as we’ve had above-average inflation recently. Because your long-term yield and return from cash typically will be lower than it is from bonds, inflation will take a bigger bite out of your payout.
Bonds have some key advantages over cash for intermediate time horizons. First, you lock in the interest rate for longer. If you buy an individual bond with a 10-year maturity, that interest rate prevails over your holding period. Second, you have appreciation potential with fixed-income investments, unlike cash. If yields drop in the future from where they are today, bond investors can benefit from appreciation in bond prices. Bonds might also gain value in an equity-market shock, whereas cash investors wouldn’t benefit from any price appreciation.
Bonds are not risk-free. If interest rates continue to rise, that could hurt bond prices, especially long-term bonds. And as with cash, bond investors are vulnerable to inflation: Higher prices mean that any interest you earn won’t go as far.
Morningstar’s Role in Portfolio framework is helpful for matching investment types to your time horizon. Cash investments are appropriate for a spending horizon of two years or less, or if you need ongoing liquidity—for example, if you’re retired. Retirees should earmark one to two years of anticipated portfolio spending in cash. If your spending horizon is two to 10 years, holding bonds is appropriate. For 10 years or beyond, equities are a reasonable bet.
Also consider your attitude toward risks and fluctuations in your portfolio. If your portfolio is too risky, is there a chance you might have to sell stocks in a downturn? If you have a tighter plan, that argues for taking a little more risk with your portfolio because you need the growth potential. If you have a plan with more assets than you need, there may be room for allocating a little more to safer investments like cash and bonds.
One would be the retiree who is willing to make course corrections in their spending. In that case, a more equity-heavy portfolio mix might be appropriate. Retirees with sizable portfolios and modest spending can also reasonably maintain more in equities than those with smaller portfolios that they’re spending more from. The more equity-heavy portfolio mixes also tend to have higher residual balances. If your goal is to have leftovers at the end of your retirement life cycle, having a little more in equities can make that more likely.
This article was provided to The Associated Press by Morningstar. For more personal finance content, go to https://www.morningstar.com/personal-finance.
Christine Benz is director of personal finance and retirement planning for Morningstar and co-host of The Long View podcast. Subscribe to her free newsletter, Improving Your Finances.
Related Links:
Morningstar: 4 Dangerous Assumptions That Could Hurt Your Retirement Plan
https://www.morningstar.com/personal-finance/4-dangerous-assumptions-that-could-hurt-your-retirement-plan
Morningstar: What High Inflation Means for Stocks, Bonds, and Your Portfolio
https://www.morningstar.com/portfolios/what-high-inflation-means-stocks-bonds-your-portfolio
Morningstar: Why Cash Is Still King for Short-Term Goals
https://www.morningstar.com/bonds/why-cash-is-still-king-short-term-goals
FILE - A tip jar contains one dollar and five dollar bills, Sept. 6, 2017 in New York. (AP Photo/Mark Lennihan, File)