
Economic performance in third quarter of 2026 and latest GDP and price forecasts for 2026
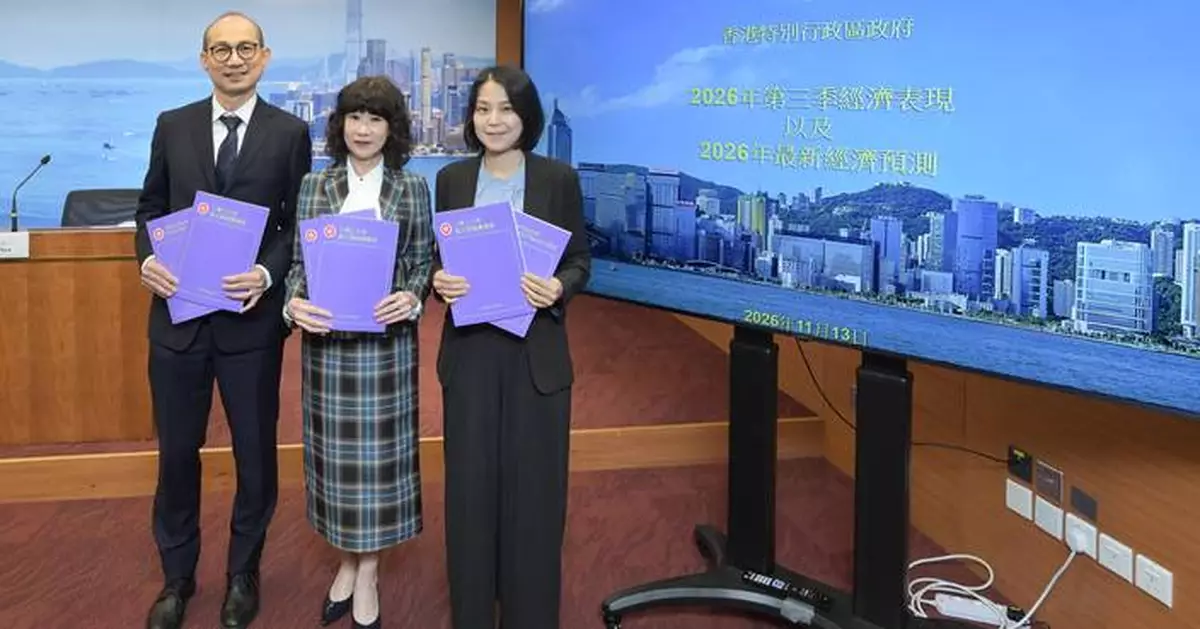
The Government released today (November 13) the Third Quarter Economic Report 2026, together with the revised figures on Gross Domestic Product (GDP) for the third quarter of 2026.
Click to Gallery
Hong Kong. Photo source: reference image
Photo source: reference image
Photo source: HKSAR Government Press Releases
Photo source: HKSAR Government Press Releases
Photo source: reference image
Photo source: reference image
Photo source: HKSAR Government Press Releases
Economic performance in third quarter of 2026 and latest GDP and price forecasts for 2026 Source: HKSAR Government Press Releases
The Government Economist, Ms Irina Fan, gave an account of the economic performance in the third quarter of 2026 and the latest GDP and price forecasts for 2026.
Hong Kong. Photo source: reference image
Main points
The Hong Kong economy expanded strongly in the third quarter of 2026, underpinned by a further pick-up in already buoyant external trade growth and solid domestic demand. Real GDP growth accelerated to 5.2% year-on-year in the third quarter, up from 4.2% growth in the preceding quarter. For the first three quarters of 2026 combined, real GDP grew by 5.1% over a year earlier, the fastest pace in five years for the corresponding period.
Growth in total exports of goods quickened to 30.3% year-on-year in real terms in the third quarter, reflecting robust trade flows amid strong global demand for artificial intelligence (AI)-related electronic products. Exports of services expanded by 4.3% in real terms over a year earlier, with all major service groups continuing to grow.
Domestic demand showed sturdy growth in the third quarter. Private consumption expenditure expanded by 2.9% in real terms in the third quarter over a year earlier, marking its sixth consecutive quarter of expansion. Overall investment expenditure picked up and rose further by 7.5% year-on-year in real terms, driven mainly by strong private sector investment spending.
The labour market stayed broadly stable in the third quarter. Both labour force and total employment increased over the preceding quarter amid the seasonal entry of graduates and school leavers. With the labour force growing faster than total employment, the seasonally adjusted unemployment rate edged up to 3.9% in the third quarter. Separately, employment earnings continued to grow solidly in the third quarter over a year earlier.
Asset market conditions were broadly stable in the third quarter. In the local stock market, the Hang Seng Index (HSI) closed the third quarter 7.6% above its end-June level amid fluctuations, outperforming several major indices elsewhere. Entering the fourth quarter, the HSI fluctuated and closed at 24 316 on November 11. In the residential property market, overall flat prices were largely stable during the quarter, while transactions remained relatively solid and broadly on par with the five-year average.
The underlying consumer price inflation edged up further in the third quarter, mainly driven by a pick-up in fuel-related components as international oil prices stayed high. Nevertheless, overall inflation remained moderate, as price pressures on other components were generally modest. The year-on-year increase in the underlying Composite Consumer Price Index (Composite CPI) edged up to 2.0% in the third quarter from 1.7% in the preceding quarter.
Looking ahead, the Hong Kong economy is poised for a strong full-year performance, supported by robust global AI investment and related trade. Entering the fourth quarter, incoming data pointed to sustained growth momentum. Exports of services are expected to benefit from continued growth in visitor arrivals and steady demand for cross-boundary financial and business services. Domestic demand is expected to remain resilient, supported by rising labour earnings, solid consumer sentiment and continued private sector investment.
Photo source: reference image
Nonetheless, uncertainties in the external environment persist. Although the United States (US) midterm election results have raised hopes of de-escalation, prolonged geopolitical tensions in the Middle East could intensify global inflationary pressures and affect major central banks' monetary policy paths. A potential resurgence of trade tensions, rising sovereign bond yields in major advanced economies amid high public debt, and a possible market correction if expectations for AI prove too optimistic also warrant close monitoring.
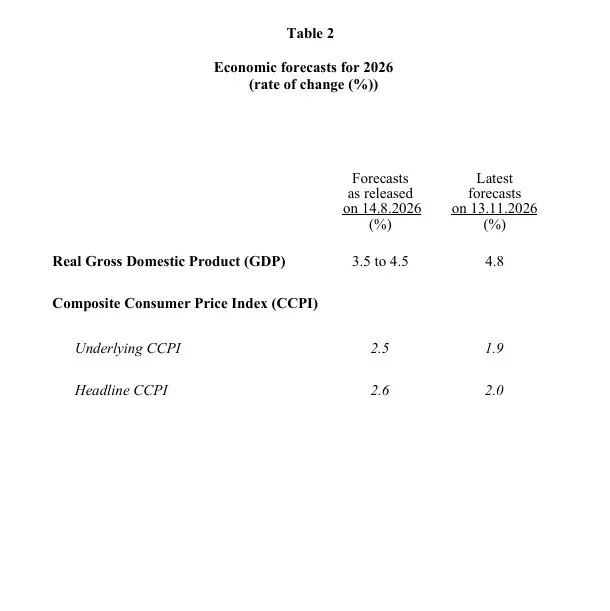
Taking into account the actual outturn in the first three quarters of the year and with the expectation of further solid growth in the fourth quarter, the real GDP growth forecast for 2026 as a whole is revised up to 4.8%, from 3.5% – 4.5% in the August round of review. The Government will continue to closely monitor the situation.
On the inflation outlook, consumer price inflation has so far been lower than expected, reflecting the slower-than-anticipated pass-through of higher international oil prices to fuel-related components, in which the alleviation effect from the Government's relevant measures including the fuel subsidies earlier also played a part. Although oil prices eased after the US midterm elections, the geopolitical situation remains uncertain, and the pass-through of elevated oil prices earlier is likely to continue into 2027. Nevertheless, as price pressures on other fronts are expected to remain largely contained, overall inflation should stay moderate. Taking into account the actual inflation outturn in the first three quarters of the year and the factors mentioned above, the forecasts for the underlying and headline consumer price inflation rates for 2026 are revised down to 1.9% and 2.0% respectively, from 2.5% and 2.6% in the August round of review.
Details
GDP
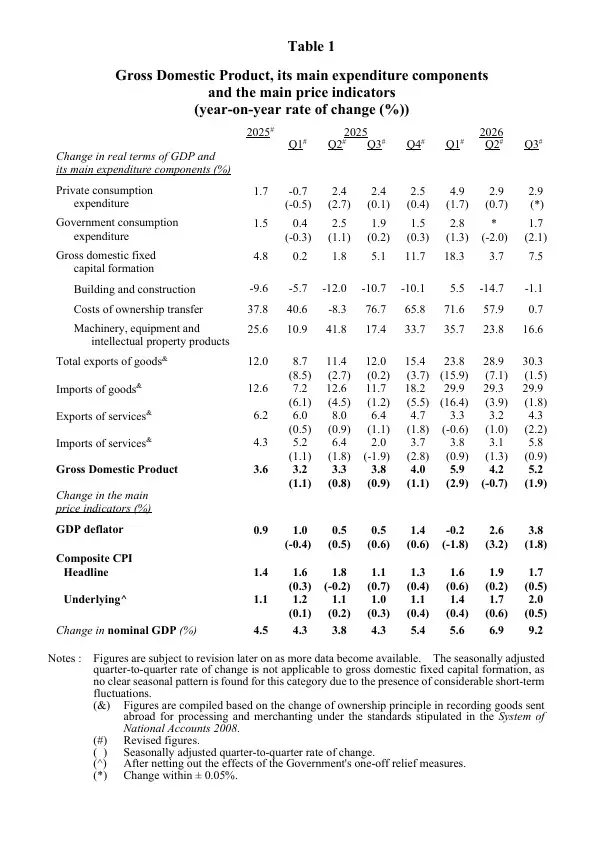
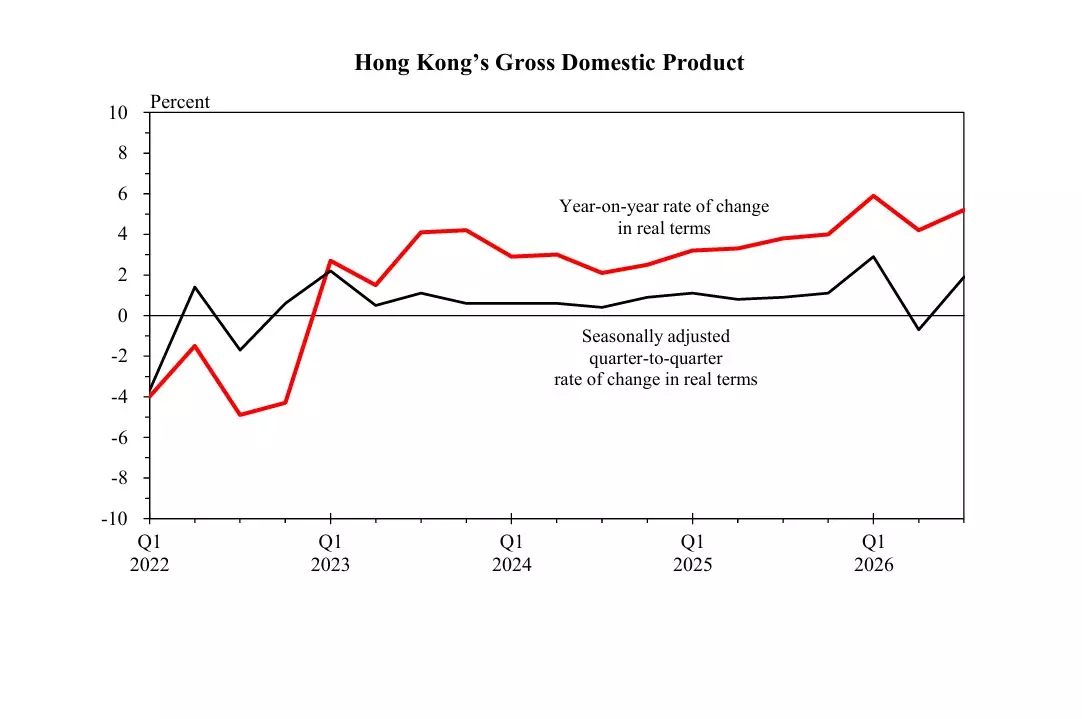
According to the revised figures released today by the Census and Statistics Department, real GDP grew by 5.2% year-on-year in the third quarter of 2026 (same as the advance estimate), following 4.2% growth in the preceding quarter. On a seasonally adjusted quarter-to-quarter comparison, real GDP increased by 1.9% in the third quarter (same as the advance estimate), after a decline of 0.7% in the preceding quarter (Chart).
Photo source: HKSAR Government Press Releases
The latest figures on GDP and its major expenditure components up to the third quarter of 2026 are presented in Table 1. Developments in different segments of the economy in the third quarter are described below.
Photo source: HKSAR Government Press Releases
External trade
Total exports of goods saw accelerated growth of 30.3% year-on-year in real terms in the third quarter, up from 28.9% in the preceding quarter. The stellar export growth reflected robust trade flows amid strong global demand for AI-related electronic products. Analysed by major market and with reference to external merchandise trade statistics, exports to the Mainland and many other Asian markets, as well as the US continued to grow markedly, and those to the European Union grew further. On a seasonally adjusted quarter-to-quarter basis, total exports of goods increased further by 1.5% in real terms in the third quarter.
Exports of services expanded by 4.3% in real terms in the third quarter over a year earlier, after rising by 3.2% in the preceding quarter. Exports of all major service groups continued to expand. Specifically, exports of transport services recorded accelerated growth, supported by robust cross-boundary traffic. Exports of travel services continued to expand, driven by resilient growth in inbound tourism. Exports of financial services and business and other services also grew mildly on the back of solid financial service and business activities. On a seasonally adjusted quarter-to-quarter basis, exports of services increased by 2.2% in real terms in the third quarter.
Domestic sector
Private consumption expenditure expanded by 2.9% in real terms in the third quarter over a year earlier, after an increase of the same extent in the preceding quarter, marking its sixth consecutive quarter of expansion. All major categories of consumption expenditure in the domestic market increased in thethird quarter over a year earlier. On a seasonally adjusted quarter-to-quarter basis, private consumption expenditure was broadly unchanged in real terms in the third quarter. Meanwhile, government consumption expenditure increased by 1.7% in real terms in the third quarter over a year earlier, after staying virtually unchanged in the preceding quarter. On a seasonally adjusted quarter-to-quarter basis, government consumption expenditure increased by 2.1% in real terms in the third quarter.
Overall investment expenditure in terms of gross domestic fixed capital formation rose by 7.5% year-on-year in real terms in the third quarter, picking up from 3.7% growth in the preceding quarter, driven mainly by strong private sector investment spending, while public sector investment spending recorded a visibly narrowed decline. Private sector investment expenditure rose by 11.6% year-on-year in real terms, marking its fourth consecutive quarter of double-digit growth, supported by a notable rise in expenditure on acquisitions of machinery, equipment and intellectual property products, as well as continued increases in expenditure on building and construction and in costs of ownership transfer.
Photo source: reference image
Labour sector
The labour market stayed broadly stable in the third quarter. Both labour force and total employment increased over the preceding quarter amid the seasonal entry of graduates and school leavers. With the labour force growing faster than total employment, the seasonally adjusted unemployment rate edged up to 3.9% in the third quarter. The median monthly employment earnings of employed persons (excluding foreign domestic helpers) recorded year-on-year growth of 3.1% in nominal terms in the third quarter.
Asset markets
Asset market conditions were broadly stable in the third quarter. In the local stock market, the HSI closed the quarter at 24 613, up 7.6% or 1 732 points over end-June, outperforming several major indices elsewhere. Average daily turnover eased to $254.2 billion in the third quarter, down 12.2% from the preceding quarter but still 1.7% above last year's annual average. Fund-raising remained robust in the third quarter, with total equity funds raised surging by 118.0% over a year earlier to $366.1 billion. Entering the fourth quarter, the HSI fluctuated and closed at 24 316 on November 11.
In the residential property market, prices held steady amid relatively active trading in the third quarter. Overall flat prices were largely stable during the quarter, with the year-to-date gain holding at 7%. The total number of transactions, as measured by the number of sale and purchase agreements for residential property received by the Land Registry, was 13 242 in the third quarter, broadly on par with the five-year average, though below the buoyant level in the first half of the year. Overall flat rentals rose further by 3% in the third quarter amid the traditional peak season.
Prices
The underlying consumer price inflation edged up further in the third quarter, mainly driven by a pick-up in fuel-related components as international oil prices stayed high. Nevertheless, overall inflation remained moderate, as price pressures on other components were generally modest. The underlying Composite CPI rose by 2.0% in the third quarter over a year earlier, accelerating from the 1.7% increase in the preceding quarter. Including the effects of the Government's one-off relief measures, the headline Composite CPI rose by 1.7% year-on-year in the third quarter, down slightly from 1.9% in the preceding quarter.
Photo source: reference image
Latest GDP and price forecasts for 2026
Looking ahead, the Hong Kong economy is poised for a strong full-year performance, supported by robust global AI investment and related trade. Entering the fourth quarter, incoming data pointed to sustained growth momentum. Exports of services are expected to benefit from continued growth in visitor arrivals and steady demand for cross-boundary financial and business services. Domestic demand is expected to remain resilient, supported by rising labour earnings, solid consumer sentiment and continued private sector investment.
Nonetheless, uncertainties in the external environment persist. Although the US midterm election results have raised hopes of de-escalation, prolonged geopolitical tensions in the Middle East could intensify global inflationary pressures and affect major central banks' monetary policy paths. A potential resurgence of trade tensions, rising sovereign bond yields in major advanced economies amid high public debt, and a possible market correction if expectations for AI prove too optimistic also warrant close monitoring.
Taking into account the actual outturn in the three quarters of the year and with the expectation of further solid growth in the fourth quarter, the real GDP growth forecast for 2026 as a whole is revised up to 4.8%, from 3.5% – 4.5% in the August round of review (Table 2). The Government will continue to closely monitor the situation.
On the inflation outlook, consumer price inflation has so far been lower than expected, reflecting the slower-than-anticipated pass-through of higher international oil prices to fuel-related components, in which the alleviation effect from the Government's relevant measures including the fuel subsidies earlier also played a part. Although oil prices eased after the US midterm elections, the geopolitical situation remains uncertain, and the pass-through of elevated oil prices earlier is likely to continue into 2027. Nevertheless, as price pressures on other fronts are expected to remain largely contained, overall inflation should stay moderate. Taking into account the actual inflation outturn in the first three quarters of the year and the factors mentioned above, the forecasts for the underlying and headline consumer price inflation rates for 2026 are revised down to 1.9% and 2.0% respectively, from 2.5% and 2.6% in the August round of review (Table 2).
Photo source: HKSAR Government Press Releases
The Third Quarter Economic Report 2026 is now available for online download, free of charge at www.hkeconomy.gov.hk/en/situation/index.htm. The Report of the Gross Domestic Product by Expenditure Component, which contains the GDP figures up to the third quarter of 2026, is also available for browse and download, free of charge on the homepage of the Census and Statistics Department, www.censtatd.gov.hk.
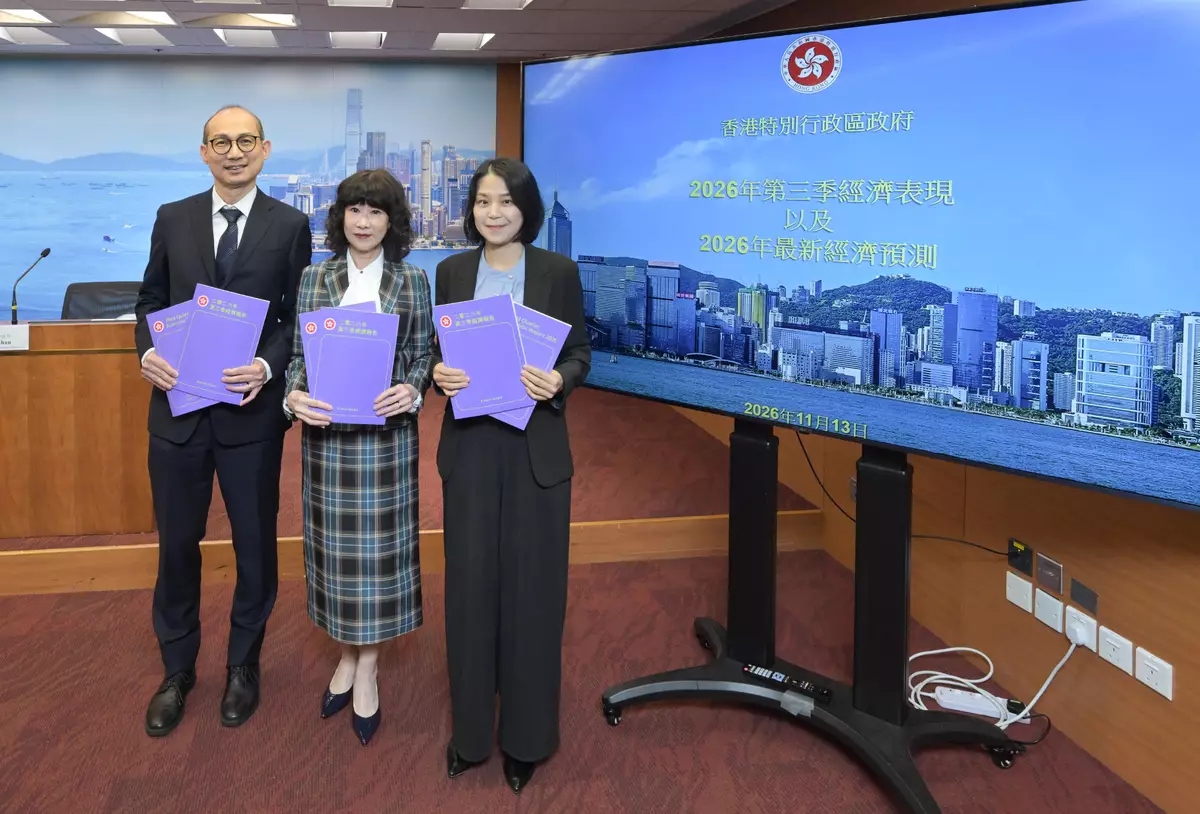
Economic performance in third quarter of 2026 and latest GDP and price forecasts for 2026 Source: HKSAR Government Press Releases