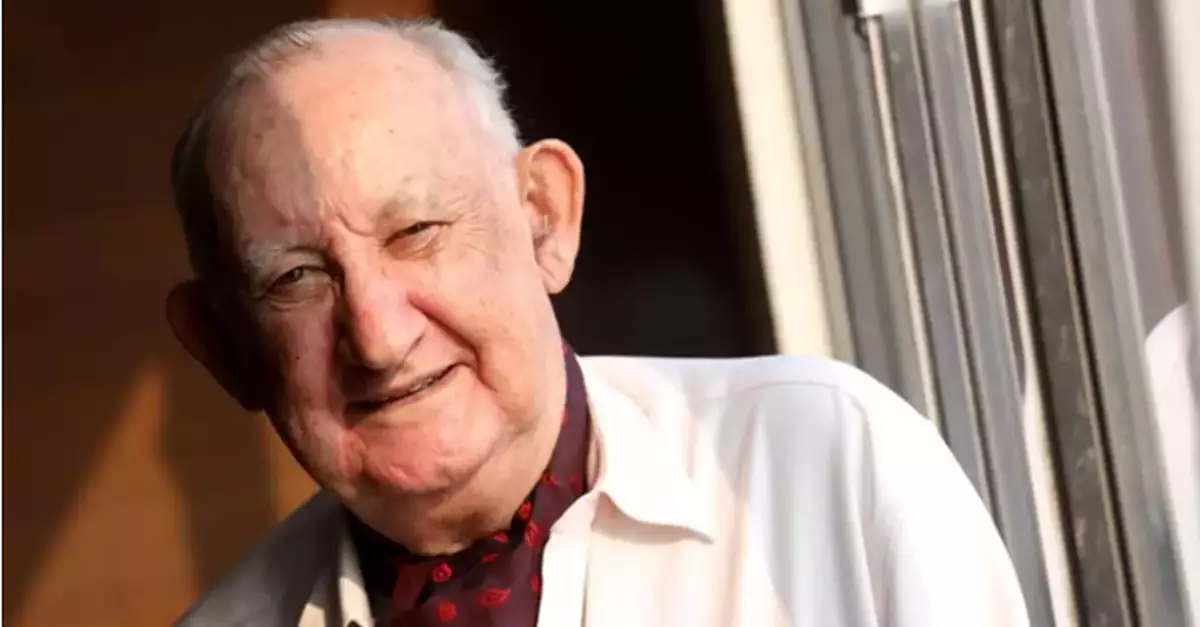
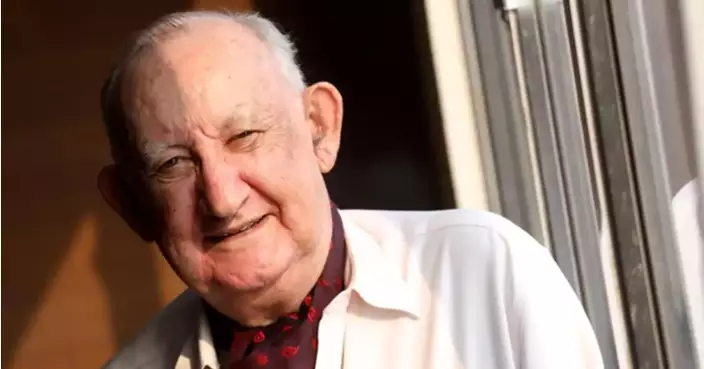
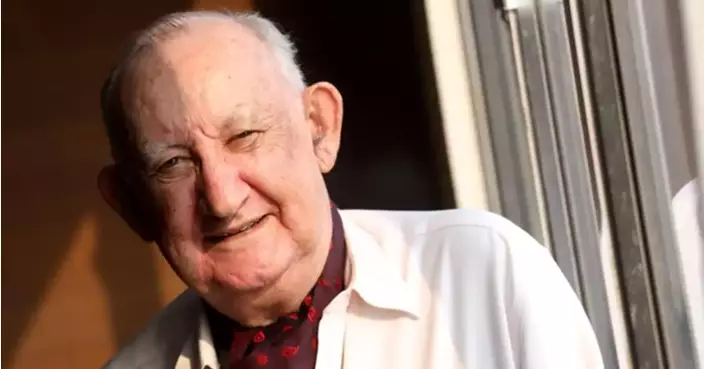
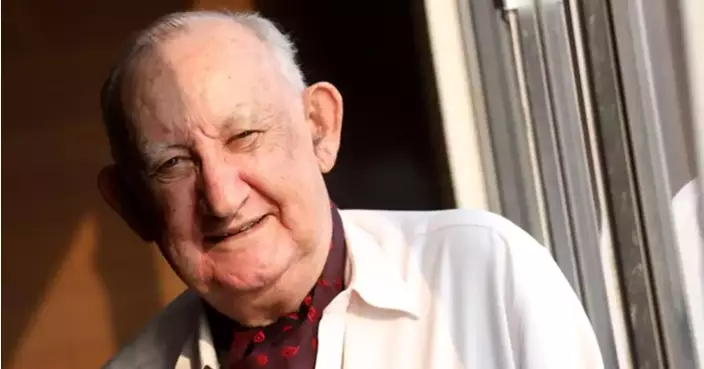
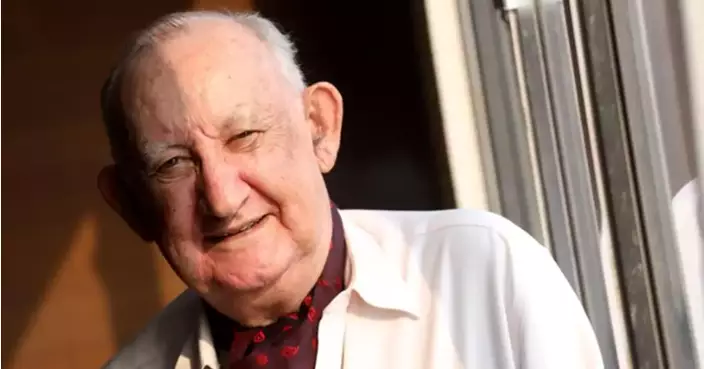
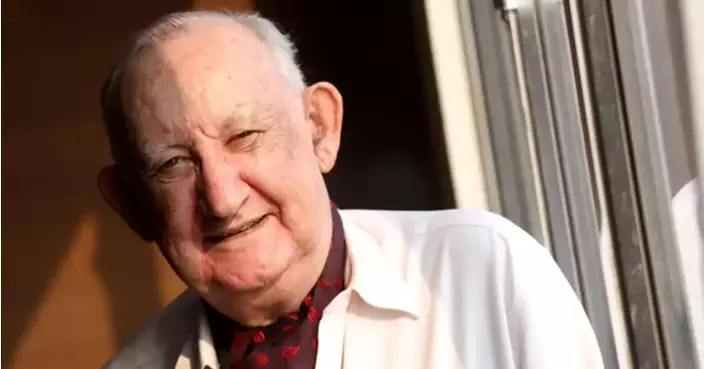
Jimmy Lai has been sentenced to 20 years jail for treason related charges and the reaction from the international media and politicians is predictable.
They all decry Hong Kong and its judicial system as being unfair and persist in calling for his immediate release from prison.
They cite his failing health as a reason for his release. He has Type 2 diabetes, which is not uncommon in Hong Kong, including among the 10,000 inmates interned in local prisons.
In passing sentence, the three judges hearing the 156-day trial, noted that Lai was the mastermind and driving force behind these conspiracies. After considering the serious and grave criminal conduct of Lai, as noted in the Reasons for Verdict, applying the totality principle, the Court was satisfied that the total sentence for Lai in the present case should be 20 years’ imprisonment.
In a show of total transparency, the sentencing document was 47 pages long. Relevant extracts were read out in court, with full copies given to lawyers, the media and uploaded on the internet.
Six other co-defendants were also sentenced to jail time ranging from 6 years and 9 months to 10 years.
Lai was convicted last month on sedition and colluding with foreign governments to overthrow the Hong Kong government. These are serious charges anywhere in the world and a sentence of 20 years for such offences is duly warranted. Undoubtedly, he will appeal.
Stanley prison, where he is interned, has full hospital facilities staffed by qualified healthcare personnel, and round-the-clock basic health care services are provided at all penal institutions. Lai is receiving the best medical treatment available. The Correctional Services Department has a full-time chaplain who co-ordinates the planning and provision of religious services and Lai, a devout Catholic, specifically asked not to receive any religious privileges. He also asked to be kept in solitary confinement so as to not mingle with other inmates. Justices of Peace visit the prison every week to hear complaints from inmates and inspect their facilities. He has not been deprived of medical or visiting rights as suggested by his children, Sebastien and Claire, who have embarked on a campaign for his immediate release.
Lai senior has been found guilty of colluding with foreign governments, yet this is exactly what his children are doing. With millions of dollars at their disposal, they have embarked on a world-wide campaign to free their father, a basic instinct, which can only be achieved with the help of a huge bank roll. They have lobbied politicians in the US, UK and EU to apply pressure on the Hong Kong judiciary and authorities to release their father. For the Lai family, colluding with foreign forces is their own salvation.
But the judiciary is totally independent, free from pressures by human rights groups, the media, politicians and, indeed, the administration. The three judges – Esther Toh Lye-ping, Susana D’Almada Remedios and Alex Lee Wan-tang – sat through gruelling evidence over a period of two years (with gaps in between) and produced a 855-page detailed document explaining the reasons behind their guilty convictions. Representatives from the UK, US and EU with a bevy of press attended the proceedings every day. The courtroom was specially configured to allow 58 seats in the public gallery and another 42 for the press in the main courtroom. Of those, 21 are allocated to local media, 14 to international outlets and seven to digital news platforms. Nothing can be more transparent than that.
This was not a “sham” trial as suggested by the Lai followers. Hong Kong is rated 6th in the Asia/Pacific region and 24th out of 143 countries worldwide by the World Justice Project Rule of Law Index, two points above the US. Its independence is beyond reproach.
Yet the western media is being used to cast doubt on the judiciary’s ruling and sentencing. Lai has been painted as a father of democracy, but “democracy” was not his rallying call. His whole campaigns have centred around separatism. He was seeking Hong Kong independence, like Alberta pulling away from Canada, California from the USA and Catalonia from Spain. All have been rebutted by their federal governments. Arrest warrants have been issued for former journalist Carles Puigdemont as leader of the Spanish revolt and now in exile in Belgium with separatism charges looming over his head.
But Jimmy Lai did not flee Hong Kong after the 2019-20 bloody riots, which he fuelled through his newspaper, Apple Daily. Instead, he stayed behind to face the music and to be hailed a martyr to the cause. It is because of this carefully orchestrated action that he got to the support of world leaders who mistakenly thought he was advocating democracy. They were fooled by a billionaire and his family into thinking that by giving him support, they were providing freedom to the people of Hong Kong. Hong Kong people have all the freedoms they want and can even criticize the government for maladministration without fear of persecution.
Democracy was never an issue. Hong Kong has a fully elected legislature, its president is elected by its members, and the Chief Executive is elected by a 1500-strong election committee – 1000 more than the US. Hong Kong has a democracy and its Basic Law (mini constitution) allows for the Chief Executive to be elected by universal suffrage sometime in the future.
Mark Pinkstone
** 博客文章文責自負,不代表本公司立場 **
Hong Kong is well positioned to be the driving vehicle for the internationalization of the Renminbi (RMB) as the city ranks third globally and first in the Asia-Pacific region in the Global Financial Centres Index in 2026.
Many countries are now trading in the Chinese yuan (RMB), accounting for more than a quarter of China's cross-border trade settlements. China uses bilateral swap lines, offshore clearing hubs, and direct trade agreements to promote the RMB globally.
Major countries and regions trading or settling transactions in RMB includes Russia, uses the RMB extensively for bilateral trade and energy payments following Western sanctions; ASEAN nations use the RMB for regional trade; the Gulf and Middle Eastern nations use local and yuan settlements, particularly for the oil trade; and other emerging and Asian partners such as Bangladesh, Pakistan, Sri Lanka and Mongolia use the RMB for specific bilateral projects, trade financing and debt settlement.
And, of course, the Belt and Road Initiative countries increasingly use the RMB for specific bilateral projects, trade financing, but it still remains secondary to the US dollar. It is only natural that China actively promotes RMB trade settlements with partner nations to bypass third party currency risks.
The role of Hong Kong’s internationalizing of the RMB was a key point in the Chief Executive John Lee’s first five-year plan and policy address to the Legislative Council last month.
This endeavor is not merely about currency exchange, he said. It encompasses a multi-faceted strategy to enhance the RMB's liquidity, deepen its offshore market, and solidify its position as a global trade and investment currency.
Hong Kong's unique "One Country, Two Systems" framework, coupled with its robust financial infrastructure and legal system, provides an ideal platform for these initiatives.
One of Hong Kong's most significant contributions is its position as the largest offshore RMB liquidity pool. This is achieved through a comprehensive ecosystem of RMB-denominated financial products and services. The city actively encourages the issuance and trading of RMB bonds (Dim Sum bonds), providing international investors with diverse investment opportunities in the currency. Furthermore, Hong Kong facilitates RMB trade settlement, making it easier for businesses globally to conduct cross-border transactions in RMB, thereby reducing foreign exchange risks and transaction costs. The expansion of RMB financing activities, including syndicated loans and private equity funds denominated in RMB and further broadens the currency's utility for international businesses.
Hong Kong continually innovates its financial market infrastructure to support RMB internationalization. The RMB Real -Time Gross Settlement (RTGS) system in Hong Kong is a cornerstone, offering a highly efficient and secure platform for interbank RMB payments and settlements. This system connects banks globally, enabling seamless RMB transfers and enhancing the currency's liquidity. The city has also been at the forefront of exploring digital RMB initiatives, with trials and pilot programs aimed at integrating the digital yuan into its financial landscape, potentially offering new avenues for cross-border RMB flows and enhancing transaction efficiency.
To deepen the offshore RMB market, Hong Kong actively promotes the listing and trading of RMB-denominated securities. The government's efforts to facilitate the inclusion of RMB trading counters in the Stock Connect schemes (connecting Hong Kong with Shanghai and Shenzhen stock exchanges) are pivotal. This allows international investors to trade mainland A-shares directly using offshore RMB, significantly boosting demand for the currency and enhancing its investment appeal. Similarly, the ongoing work to enable the inclusion of REITs (Real Estate Investment Trust) in mutual market access schemes and to streamline procedures for dual listing further diversifies RMB investment options.
Beyond direct financial mechanisms, Hong Kong fosters RMB promotion through strategic collaborations and policy alignments with mainland China. The city's active participation in the Greater Bay Area (GBA) development provides a natural extension for RMB usage. Initiatives like enhancing cross-border data interchange (e.g., Commercial Data Interchange connecting with the Trade Single Window) and promoting cross-border payment systems (linking with UnionPay) aim to facilitate RMB flows and integration within the GBA, creating a larger economic sphere where RMB is the preferred currency for trade and investment.
Hong Kong's role as a risk management center is crucial for RMB internationalization. By offering sophisticated hedging instruments and risk management solutions for RMB-denominated assets and liabilities, Hong Kong enhances confidence among international investors and businesses in using the currency. The city's robust regulatory framework and legal certainty provide a secure environment for RMB financial activities, distinguishing it as a trusted platform for the currency's global expansion.
According the Chief Executive of the Hong Kong Monetary Authority, Eddie Yue, to consolidate Hong Kong’s role as the global offshore RMB hub, we need an enabling ecosystem that is characterised by easy access, “stickiness” and growth opportunities for international capital.
With the joint efforts of the banking sector, Hong Kong will continue to strengthen its offshore RMB hub function in support of the real economy, unlocking greater potential to drive RMB internationalisation.
In essence, Hong Kong's promotion of the RMB is a strategic, multi-pronged approach that leverages its strengths as an international financial center, its advanced infrastructure, and its close ties with the mainland. By continually enhancing liquidity, broadening product offerings, and fostering seamless cross-border flows, Hong Kong remains indispensable in the journey towards the RMB's greater global prominence.