When Trump campaigned, he said that he did not start a war in four years of his first term as president of the United States, and that he did not like war. He began his second term as president on January 20, and less than two months later, on March 15, he launched his first war since taking office, with massive air strikes against Yemen. At the same time, he repeatedly declared to the world that he wanted to "take back" control of the Panama Canal, not to mention the use of military means to obtain Greenland.
It is not difficult to see Trump's intention to control the world's maritime transportation channels as a deployment for the whole world and global trade. As we all know, there are four fortresses on the world's seaborne trade routes, the first of which is the Strait of Malacca where the Pacific Ocean enters the Indian Ocean and the Arabian Sea. The strategic location of this fortress has been a battleground since ancient times, and it is especially important for China, which accounts for 60% of its global trade through the strait. The United States, which already has a military base in Singapore, has effectively taken control of the Strait of Malacca. The second stronghold is the Panamanian Port and Canal, where China has 20% of its trade turnover. Trump's big push to "take back" the Panama Canal is to control the shipping lanes between the Atlantic and Pacific Oceans, and to kill 20% of China's trade at any time. The third is the Mediterranean Sea and the Red Sea fortresses, as long as this route is controlled, the trade volume here can be completely controlled by the United States. This also explains why Trump has launched an airstrike on Yemen at the Red Sea Coast. The fourth fortress is the Arctic Ocean Route. As the planet warms and glaciers melt, the Arctic Ocean shipping lanes are getting busier; China's trade to Europe can be shortened by about 40 percent through this route. When Trump was in his first president term, he had already said that he wanted to buy Greenland, and now he has threatened to take control of Greenland by military means if the purchase nor encouraging Greenland's independence does not work. Mr. Trump did this ostensibly for the island's rare earth resources, but more importantly for control of the Arctic Ocean shipping lanes.
External ports are strategic assets for any country, and commercial operations can play a good role in a healthy global trade ecology. Today, however, the United States is clearly hostile to China, and its president is so ostentatiously seeking control of the world's most important ports and sea routes in order to one day cut off China's overseas trade. Knowing this background, it is not rocket science to judge whether the purchase and sale of Panama port terminals is a simple and pure commercial deal.
Ocean
** 博客文章文責自負,不代表本公司立場 **
On June 22, 2025, mainland China’s Online Payment Interbank Clearing System (NetsUnion) and Hong Kong’s Faster Payment System (FPS) officially interconnected. On the inaugural day of "Cross-Border Payment Connect," Northbound remittances (Hong Kong to the mainland) logged roughly 6,900 transactions averaging RMB 800 each, while Southbound remittances reached 19,000 transactions averaging RMB 3,100 each—enabling instant, phone-number-based cross-border transfers.
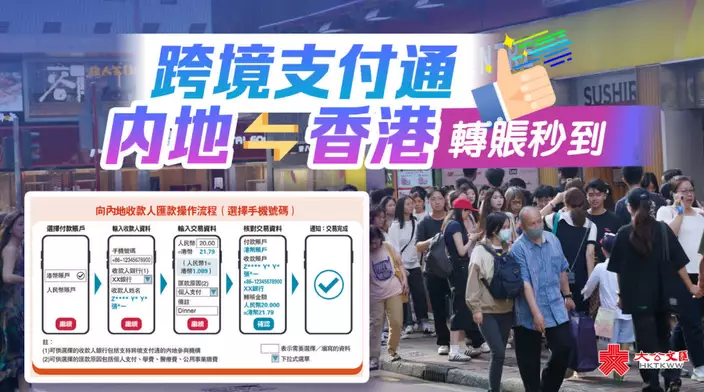
Hong Kong's FPS interconnects with the mainland's online payment system as Cross-Border Payment Connect launches on June 22, 2025. (Source: Ta Kung Wen Hui Net photo)
Within a single year, participating institutions expanded from an initial batch of 12 to 24 in Hong Kong and 14 on the mainland, with WeChat Pay HK added to the roster and the system facilitating its first departure tax refunds. Yet this represents merely the tip of China’s evolving financial infrastructure: while global markets debate "de-dollarization," China’s QR code payment architecture has quietly woven a digital network spanning over 200 countries and regions.
Inbound Travel: From "Payment Isolated Islands" to "Scan-and-Go Freedom"
Payment friction experienced by foreign travelers in China was once a prominent topic of public discourse. The structural breakthrough stemmed from regulatory relaxation: the People’s Bank of China (PBOC) instructed payment operators to raise single-transaction limits for international visitors from $1,000 to $5,000, and annual cumulative transaction caps from $10,000 to $50,000.
The market response was immediate. Data from NetsUnion Clearing Corporation indicates that since 2026, mobile payment transaction volume by foreign visitors in China grew roughly 70% year-on-year, with total transaction value rising 40%. The "Foreign Cards, Domestic Binding" framework (linking international credit cards to domestic QR payment apps) now serves users across more than 200 countries and regions, while the "Overseas Wallets, Domestic Use" model integrates 16 major international e-wallets. During the 2026 May Day holiday, mobile transactions by overseas travelers surged 45.15% year-on-year—with visitors from Hong Kong, Kazakhstan, and Malaysia favoring their native e-wallets to scan and pay. The simple act of scanning a QR code, an everyday norm in China, has become the global traveler's default motion.
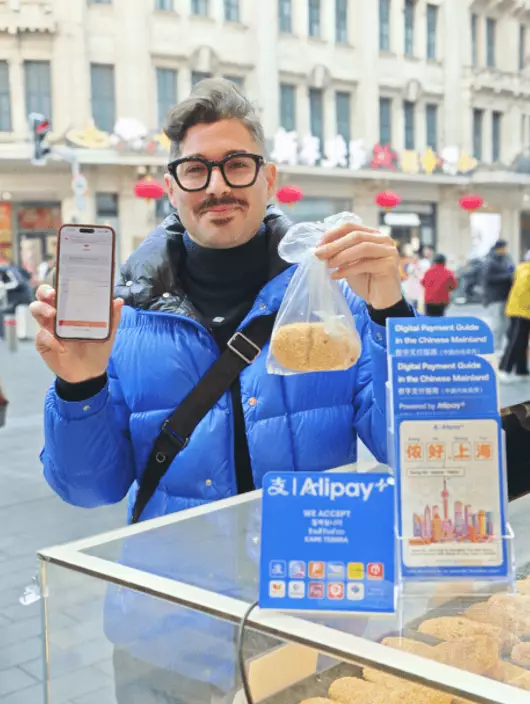
An Italian traveler in Shanghai holding a smartphone alongside a freshly made jianbing (savory crepe). (Source: ShineGlobal photo)
Going Global: Managing Overseas Travel on a Single Smartphone
Going Global: Managing Overseas Travel on a Single Smartphone
The outbound payment infrastructure is equally expansive. WeChat Pay’s cross-border operations cover 78 countries and regions across 36 currencies. In April 2026, payment QR systems across South Korea, Sri Lanka, Thailand, Malaysia, and Singapore connected directly with WeChat Pay—allowing Chinese tourists on the streets of Bangkok to pay like locals without toggling apps or converting foreign currency.
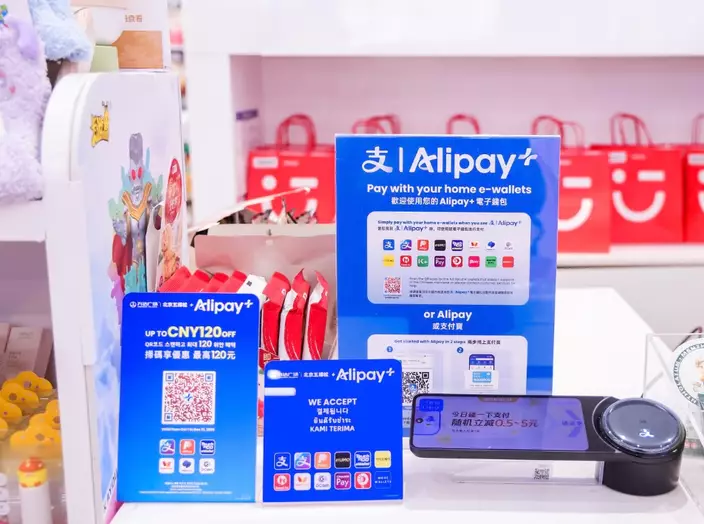
Ant International’s Alipay+ platform operates at an even larger scale: connecting 50 global e-wallets, covering 220 markets, and serving over 150 million merchants and 2 billion user accounts worldwide. In Indonesia alone, Alipay is linked to more than 40 million merchant QRIS codes. Meanwhile, the "Domestic Wallets, Overseas Use" network allows Chinese consumers to pay abroad using their domestic digital wallets across 220 countries and regions at over 70 million merchant terminals.
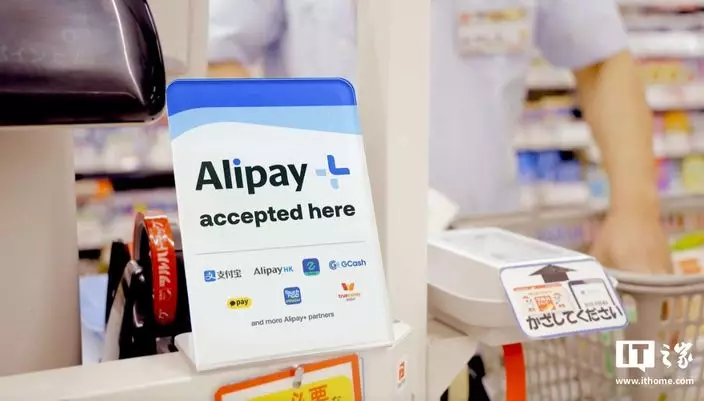
An "Alipay+ Accepted Here" standee positioned at a convenience store checkout counter in Japan. (Source: IT Home photo)
Hong Kong: The Strategic Bridgehead of Financial Connectivity
In this payment transformation, Hong Kong functions as both a crucial co-architect and a primary beneficiary. Cross-Border Payment Connect directly links the mainland’s NetsUnion with Hong Kong’s FPS. The 2026 Policy Address announced that the Hong Kong Monetary Authority (HKMA) will explore expanding its user base to facilitate seamless cross-border living, employment, and retirement services.
In July 2026, Hang Seng Bank became the first Hong Kong banking partner to collaborate with Alipay+, enabling its mobile banking customers to scan and pay across 100 million merchants in over 55 countries and regions. That same month, Hong Kong Exchanges and Clearing (HKEX) signed a memorandum of understanding with the Cross-Border Interbank Payment System (CIPS) to work toward becoming a Direct Participant in CIPS. As of June 2026, CIPS boasted 210 Direct Participants, with network reach extending across 191 countries and regions and over 5,200 banking institutions worldwide.
Conceptual illustration of CIPS cross-border financial connectivity. (Source: Phoenix Net graphic)
Petro-RMB: Cracks Appear in the Dollar’s Strongest Fortress
Most significantly, this clearing architecture is reaching into the core of global finance: crude oil settlement. According to market data from Chinese financial institutions, in March 2026, RMB settlement in China’s crude oil trade with the Middle East surpassed 41% for the first time, overtaking the euro as the corridor's second-largest transaction currency. Meanwhile, the US dollar's historical market share of over 90% in that trade corridor moderated to 52%.
To place this in precise context: this shift represents a strategic breakthrough within a key bilateral energy corridor rather than a total realignment of global trade. According to SWIFT data, the RMB’s global payment share stood at 2.85% in April 2026, indicating that challenging the dollar's global position remains a long-term evolution.
Yet the institutional channels are now open: Iran’s crude exports to China are reported to be fully settled in RMB, while Saudi Aramco’s RMB settlement share for oil shipments to China has risen steadily. On April 2, 2026, CIPS single-day transaction volume reached a record RMB 1.22 trillion—nearly double its February daily average. Driven by geopolitical shifts, sanctions, and Middle Eastern market realignments, the de-dollarization pace of the "Petro-RMB" is accelerating.
The Invisible Fabric of Institutional Power
This represents perhaps the most quiet yet far-reaching chapter of the "Chinamaxxing" narrative: unaccompanied by viral mascot pandas or robotic demonstrations, a simple scan of a QR code extends from street-side food stalls to the decks of international oil tankers.
Two decades ago, outbound Chinese travelers relied on foreign currency exchanges and international credit cards; today, arriving international visitors learn to link their cards to domestic payment networks. Meanwhile, the term "petrodollar"—which defined energy finance for half a century—is being supplemented by "Petro-RMB" on commercial invoices. Between a 41% share in the Middle East energy corridor and a 2.85% global payment footprint lies a long journey, but the structural direction is set.
Behind this trajectory sits a robust institutional framework: over the past decade, through NetsUnion, CIPS, and Cross-Border Payment Connect, China has constructed a unified payment infrastructure—standardized, interconnected, autonomous, and secure. This architecture reflects the systemic strengths of national security: true financial sovereignty relies on independent payment channels. A coordinated, nation-wide strategic approach ensures this primary financial artery operates reliably amid geopolitical volatility. Ultimately, the resilience of a payment network mirrors the underlying strength of national capability. The shift in everyday payment habits serves as a clear metric of institutional influence; as the RMB transitions from tourist digital wallets to international commodity contracts, China's payment expansion evolves from a consumer story into the foundational rewriting of the global monetary order.